
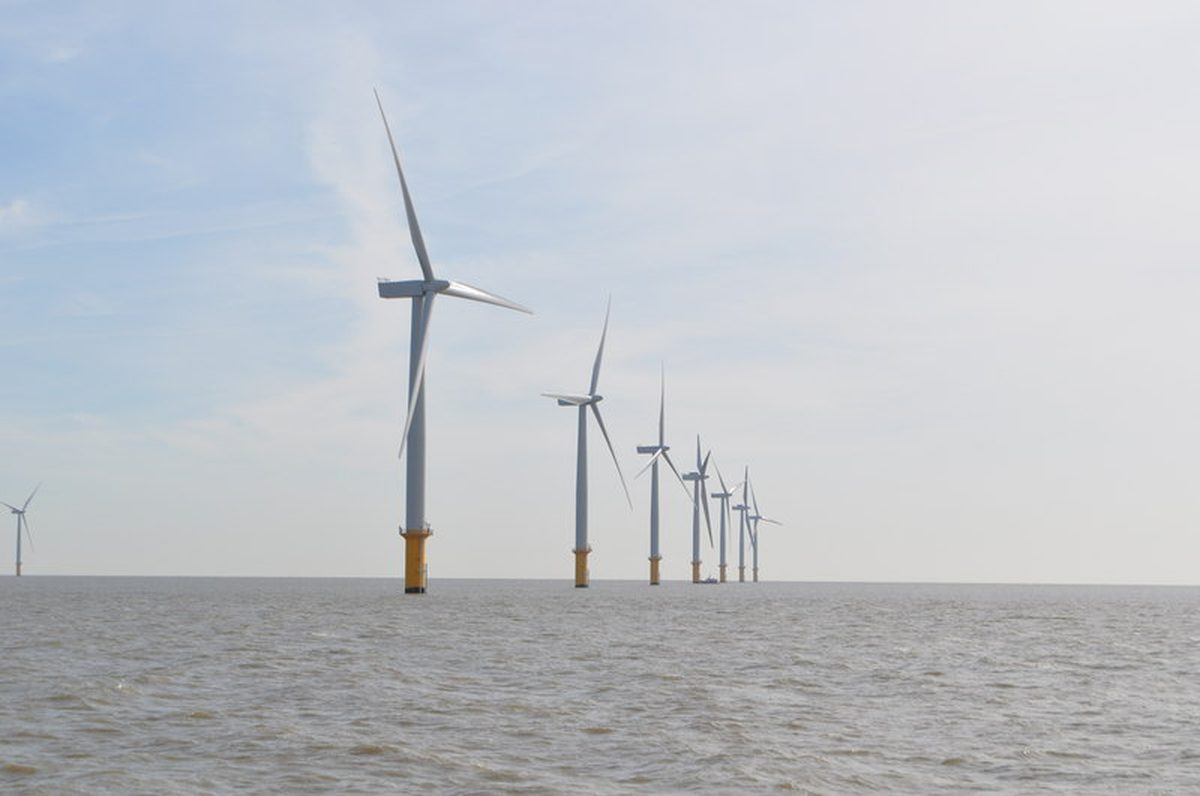
- Ørsted has exercised a long-standing buyback right to take full ownership of the 172 MW Gunfleet Sands 1 & 2 offshore wind farm for £15 million ($20 million).
- The deal, expected to close in November 2026, removes JERA and the Development Bank of Japan (24.95% each) as partners, giving Ørsted freedom over the farm’s late-life options.
- The price works out to roughly £0.17 million per MW acquired, about a twentieth of the cost of building new offshore capacity in UK waters.
Ørsted is about to become the sole owner of one of Britain’s first offshore wind farms. The Danish developer said on Monday it would pay £15 million (about $20 million) for the remaining 49.9% of the 172 MW Gunfleet Sands offshore wind farm off the Essex coast, an asset that has been turning in the Thames Estuary since 2010 and still powers more than 125,000 UK homes a year.
The stake changes hands from two Japanese partners: power generator JERA, which held 24.95%, and the Development Bank of Japan, which held another 24.95%. Ørsted already owned 50.1%. According to Reuters’ reporting on the 12 October announcement, the transaction follows a buyback right written into the original partnership agreement and is expected to close in November 2026.
What £15 million buys: freedom over an ageing asset
The economics of the deal come down to late-life asset management, not new construction. Ørsted told Reuters the move gives it room to weigh the farm’s future options, including a potential lifetime extension. That is a very different calculation from the one facing new projects in British waters, where developers are wrestling with 15-year borrowing highs and auction strike prices near £91/MWh (2024 prices) in the AR7 round earlier this year.
Gunfleet Sands 1 & 2, built between 2008 and 2010, consists of 48 Siemens SWT-3.6-107 turbines, each rated at 3.6 MW with a 107-metre rotor and standing 129 metres to the blade tip. At 172 MW the farm was a flagship of the UK’s Round 2 programme. Sixteen years later, the technology has moved on dramatically: the turbines being installed on the newest British projects rate 13–15 MW apiece, with rotors above 220 metres. A single modern machine can now replace roughly four Gunfleet Sands turbines.
A growing club: keeping old wind farms spinning
Gunfleet Sands is joining a growing group of first-generation offshore farms approaching a decision point. Across Europe, the earliest offshore projects commissioned between 2007 and 2012 are reaching the end of their original 20–25 year design lives, and owners are choosing between decommissioning, repowering with larger turbines, or extending operations after structural reassessment. Germany’s first offshore wind farm, Alpha Ventus, changed hands recently in a deal driven by exactly this kind of late-life calculation (we covered it in October 2026).
The advantage of a lifetime extension is obvious once the arithmetic is laid out. Extending an existing, grid-connected, permitted asset avoids the multi-year development slog of a new project: no fresh seabed lease, no new grid connection, no planning inquiry. The foundations, cables and substation at Gunfleet Sands are already in place, and 16 years of operational data give engineers a detailed picture of what needs attention.
In that sense the Gunfleet Sands deal also reads as portfolio rotation. The same year Ørsted is selling down equity in its newest projects to fund construction (Apollo-managed funds took 50% of Hornsea 3 for DKK 39 billion), it is consolidating full ownership of a fully depreciated veteran for a fraction of that sum. Capital raised against new-build megawatts is being recycled partly into squeezing more decades from sunk ones, a pattern that has become standard across the sector’s maturing European fleets.
£174k per MW vs. £3.98M New-Build: The Gunfleet Sands Arithmetic
Paying £15 million for 49.9% of 172 MW implies roughly £174,000 per megawatt for the capacity acquired. Compare that with the cost of building equivalent new capacity today: the UK’s official DESNZ/Arup cost study of July 2025 puts fixed-bottom offshore wind capex for projects reaching operation in 2028–2032 at £3,321–£4,439 per kW, with a medium case of £3,976 per kW, essentially £3–4.4 million per MW. On that benchmark, Ørsted is securing mature capacity at roughly one-twentieth to one-twenty-fifth of new-build capital cost.
| Measure | Cost per MW |
|---|---|
| Gunfleet Sands buyback (£15M / 85.8 MW acquired) | ~£174,000 |
| UK new-build capex (DESNZ/Arup medium case) | £3,976,000 |
| Revolution Wind, US ($6.2B / 704 MW) | ~£6,500,000 |
| UK fixed-bottom annual opex (DESNZ/Arup range) | £73,700–£207,200 |
A cross-check against a new build in U.S. waters sharpens the comparison. Revolution Wind carries a $6.2 billion investment figure for 704 MW, about $8.8 million per MW, or roughly £6.5 million at typical exchange rates, per our coverage of its final turbine installation. Against that yardstick, Gunfleet Sands at £174,000 per MW isn’t a twentieth of new-build cost; it’s closer to a thirty-seventh. The DESNZ/Arup benchmark is the fairer like-for-like comparison, but the U.S. figure shows how punishing new offshore construction has become, and why keeping a depreciated, grid-connected veteran spinning may be the best megawatt deal in Ørsted’s portfolio.
That arithmetic does not mean the £15 million is the full cost of ownership. Extending the farm’s life will require investment of its own: updated electrical systems, structural surveys, possibly new blades or gearboxes. Operating a 2010-vintage farm is labour-intensive compared with the newest automated assets. The DESNZ/Arup study puts annual operating expenditure for UK fixed-bottom projects at £73,700–£207,200 per MW, and financing costs near 15-year highs are squeezing every offshore developer’s margins, Ørsted included.
But the context matters. Ørsted currently operates 12 UK offshore wind farms supplying roughly 7% of the country’s electricity, and in a market where new final investment decisions have all but dried up, squeezing more decades out of sunk assets is the cheapest megawatt available. The strategic logic is simple: when new capacity is hard to finance, the existing fleet becomes the portfolio’s growth engine.
For readers new to how these machines work, our guide to wind turbines explains how a modern turbine converts wind into grid electricity, and why a 280-metre rotor harvests energy in a different league from the 107-metre machines at Gunfleet Sands.